Services
Medicare
Medigap: Comprehensive Supplement Insurance
Medigap, also known as Medicare Supplement Insurance, is designed to help fill the “gaps” in Medicare coverage. Offered by private insurers, Medigap plans can cover some of the out of pocket costs that Original Medicare (Parts A & B) does not fully pay for, including copayments, coinsurance, and deductibles.
Who is Eligible for Medigap?
To be eligible to purchase a Medigap policy, you must meet the following criteria:
- Enrollment in Medicare Parts A & B: You must be enrolled in both Medicare Part A and Part B.
- Residency: You must live in the state where the policy is offered.
- Age: Typically, you must be 65 or older. However, some states offer Medigap plans to individuals under 65 who have a disability or end-stage renal disease.
- Understanding the Medigap Open Enrollment Period
The Medigap Open Enrollment period is a crucial time to purchase your Medicare Supplement plan. This period begins on the first day of the month in which you turn 65 and are enrolled in Medicare Part B. During this six-month window, you have a guaranteed right to buy any Medigap policy sold in your state, regardless of any preexisting health conditions. In certain states, you can purchase a plan as soon as you are enrolled in Medicare Part B, even if you are not yet 65.
For more detailed information on Medigap and how it can benefit you, visit Medicare.gov
Contact Ohara Insurance Agency
At Ohara Insurance Agency, we specialize in helping you find the right Medigap plan to suit your needs. Our experienced agents are ready to assist you with any questions you have about Medicare Supplement Insurance.
Medicare Part D
Understanding Medicare Part D Coverage: A Guide to Prescription Drug Benefits
Prescription medications can be a significant part of healthcare costs as we get older. Medicare Part D is designed to help Medicare beneficiaries pay for prescription medications, but understanding how Part D works can be confusing.
At Ohara Insurance, we help individuals understand their Medicare coverage options so they can make informed decisions based on their medications, healthcare needs, and budget.
Whether you’re new to Medicare or reviewing your current coverage, understanding Medicare Part D prescription drug coverage is an important part of your overall Medicare planning.
What Is Medicare Part D?
Medicare Part D is Medicare’s prescription drug coverage. It helps pay for many brand-name and generic prescription medications.
Part D coverage is offered by private insurance companies that are approved by Medicare. You can generally get prescription drug coverage in one of two ways:
- A standalone Medicare Prescription Drug Plan (PDP) that works alongside Original Medicare
- A Medicare Advantage Plan that includes prescription drug coverage
Most Medicare Advantage plans include Part D coverage. If you have Original Medicare, you can generally enroll in a standalone Part D plan.
What Does Medicare Part D Cover?
Each Medicare drug plan has its own list of covered medications, called a formulary. Formularies can vary from one plan to another.
A plan may cover:
- Generic prescription drugs
- Brand-name prescription drugs
- Certain specialty medications
- Many recommended adult vaccines
- Other outpatient prescription medications included on the plan’s formulary
Medicare Part D generally covers recommended adult vaccines covered under Part D, including vaccines for shingles, RSV, and whooping cough, without a copayment or deductible when applicable under current Medicare rules.
One of the most important things to check when comparing Medicare Part D plans is whether your specific prescriptions are covered.
How Much Does Medicare Part D Cost?
The cost of Medicare Part D varies depending on the plan you choose. Your expenses may include:
- Monthly premium: The amount you pay for your prescription drug plan each month.
- Deductible: The amount you may pay before your plan begins sharing the cost of covered prescriptions.
- Copayments: A fixed amount you pay for certain medications.
- Coinsurance: A percentage of the medication’s cost you pay.
In 2026, a Medicare drug plan’s deductible cannot be higher than $615, although some plans have no deductible.
Your prescription costs can also depend on the medication’s tier, the pharmacy you use, and whether that pharmacy has preferred pricing with your plan.
The Medicare Part D $2,100 Out-of-Pocket Limit in 2026
One of the most important changes to Medicare prescription drug coverage is the annual out-of-pocket limit.
For 2026, your out-of-pocket costs for covered Part D prescription drugs are limited to $2,100. Once you reach that limit, you pay $0 for covered Part D drugs for the remainder of the calendar year.
This can provide important financial protection for people who take several medications or expensive prescriptions.
Keep in mind that not every healthcare expense counts toward the Part D limit. The limit applies to covered Part D prescription drugs and is subject to Medicare’s rules.
Understanding the Medicare Part D Coverage Stages
Medicare Part D generally has three coverage stages.
1. Deductible Stage
If your plan has a deductible, you pay the applicable costs for covered prescriptions until you meet that deductible.
Not every Part D plan has a deductible, and the deductible amount varies by plan. For 2026, the maximum deductible is $615.
2. Initial Coverage Stage
After meeting your deductible, you generally pay your plan’s applicable cost-sharing amount for covered medications.
For 2026, Medicare states that you generally pay 25% of the cost of covered generic and brand-name drugs until your applicable out-of-pocket spending reaches $2,100.
3. Catastrophic Coverage
Once you reach the $2,100 annual out-of-pocket threshold for covered Part D drugs, you pay nothing for covered Part D drugs for the remainder of the calendar year.
What Is a Medicare Part D Formulary?
A formulary is the list of prescription drugs that a Medicare drug plan covers.
Two Medicare Part D plans may have very different formularies. Even if two plans have similar premiums, the plan that looks less expensive may not be the better choice if your prescriptions are placed on a higher-cost tier or aren’t covered.
When comparing plans, consider:
- Are all of your prescriptions covered?
- What tier is each medication in?
- What will you pay at your preferred pharmacy?
- Is mail-order pharmacy available?
- Are there restrictions such as prior authorization or step therapy?
- What is the plan’s premium and deductible?
Medicare confirms that drug costs can vary based on the medications you take, their formulary tier, the pharmacy you use, and the phase of coverage you’re in.
What Happens If You Don’t Enroll in Part D?
You don’t necessarily have to enroll in Part D immediately if you have other creditable prescription drug coverage.
Creditable coverage is prescription drug coverage that’s expected to pay, on average, at least as much as standard Medicare prescription drug coverage. Employer or union coverage, TRICARE, and certain VA or other coverage may qualify.
However, going without Part D or other creditable prescription drug coverage for 63 days or more after you’re eligible can potentially result in a Part D late enrollment penalty.
The penalty generally adds 1% of the national base beneficiary premium for each full month you went without creditable coverage. The penalty can continue for as long as you have Medicare prescription drug coverage.
That’s why it’s important to understand your prescription coverage before deciding to delay enrollment.
Can Medicare Part D Help Lower Prescription Costs?
Depending on your income and resources, you may qualify for Extra Help, a Medicare program designed to help with prescription drug costs.
For 2026, people who qualify for Extra Help can have a $0 plan premium and $0 deductible, with limited copayments for covered prescriptions.
There are also other programs and strategies that may help eligible Medicare beneficiaries manage prescription costs.
How Should You Compare Medicare Part D Plans?
The plan with the lowest monthly premium isn’t necessarily the plan that will cost you the least overall.
When reviewing Medicare prescription drug plans, look at your total estimated annual cost, including:
- Monthly premiums
- Deductibles
- Prescription copayments
- Coinsurance
- Pharmacy costs
- Drug tiers
- Your specific medications
- Whether your preferred pharmacy is in the plan’s network
Your prescription list should be one of the first things you review when comparing plans.
When Should You Review Your Medicare Prescription Drug Coverage?
Your prescription needs can change over time. A medication may be added, removed, or moved to a different formulary tier. Your preferred pharmacy may also change.
It’s a good idea to review your Medicare drug coverage during Medicare’s annual enrollment period and whenever your prescription needs change significantly.
Don’t choose a Medicare Part D plan based solely on its monthly premium. The right plan depends on your individual medications and expected prescription costs.
Get Help Understanding Your Medicare Options
Medicare Part D can be an important part of protecting your healthcare budget, particularly if you take multiple prescriptions.
At Ohara Insurance, we can help you understand your Medicare options and compare coverage based on your individual needs. Whether you’re enrolling in Medicare for the first time or reviewing your current prescription drug coverage, having the right information can make the process much easier.
Ready to review your Medicare coverage?
Get a Quote Today
Contact Ohara Insurance to learn more about Medicare coverage options and find out what plans may be available to you.
Important: Medicare plan benefits, premiums, formularies, pharmacy networks, and costs can change annually. Always verify current plan details before enrolling. This article is for educational purposes and is not a substitute for official Medicare plan documents or personalized insurance advice.
D
To enroll in a Prescription Drug Plan, you must go through a private insurer, such as our trusted partner, Senior Advisors. Here’s what you can expect in terms of costs:
- Monthly Premium: A recurring fee you pay each month.
- Yearly Deductible: An annual amount you must pay out of pocket before your coverage begins.
- Coinsurance: A percentage of the cost you pay for your prescriptions.
- Copay: A flat fee you pay for some of your prescription costs.
For more information on Medicare Part D plans and how they can benefit you, visit [Medicare.gov](https://www.medicare.gov).
Contact Ohara Insurance Agency
Ohara Insurance Agency is dedicated to helping you navigate the complexities of Medicare. Our team is ready to assist you in finding the right Medicare Part D plan to meet your needs.
.
Ancillary Services Dental,Vision & Travel
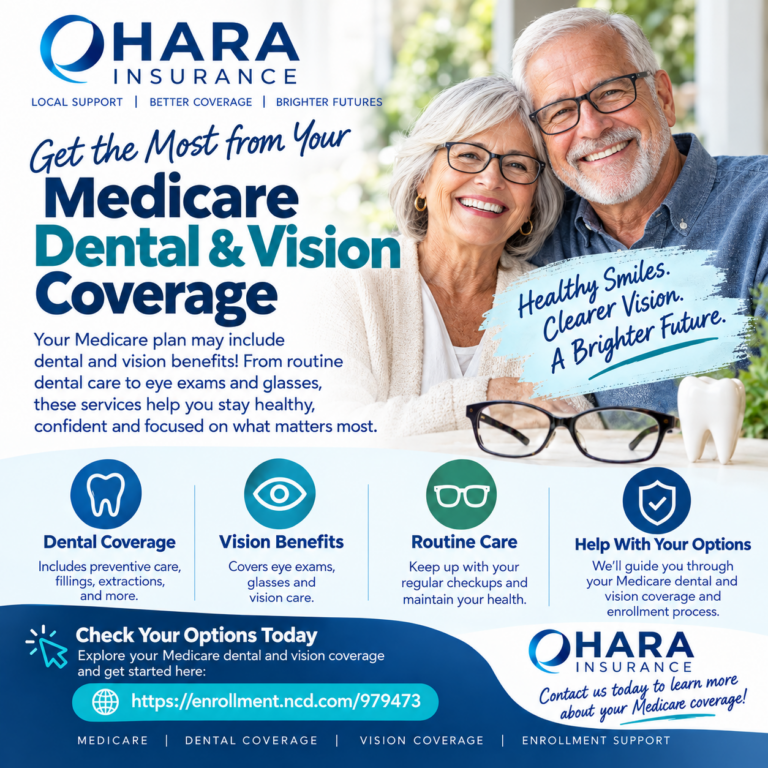
Ancillary services such as dental, vision, and travel insurance are essential additions to your health coverage, providing comprehensive care and peace of mind.
- Dental insurance helps cover routine checkups, cleanings, and major procedures, ensuring your oral health is always in top shape.
- Vision insurance supports your eye care needs, covering regular eye exams, glasses, and contact lenses.
- Travel insurance is a must-have for frequent travelers, offering protection against unexpected medical emergencies, trip cancellations, and lost luggage.
At Ohara Insurance Agency, we offer a range of ancillary services to complement your primary health insurance, ensuring you have complete coverage wherever you go. For more information on how these services can benefit you contact us today.
At Ohara Insurance Agency, we specialize in helping you navigate the complexities of Medicare. Our team is ready to assist you in finding the right Medicare Part D and Medigap plan to meet your needs. Contact us with any questions about Medicare Medigap Supplement Insurance.